Why Your Balance-to-Limit Ratio is the Most Important Number You Have
I’ll never forget the cold sweat I broke into when the loan officer at my local credit union squinted at his screen and sighed. I had just spent six months aggressively paying down my smallest balances, thinking I was a financial hero. But my score hadn’t budged an inch. I felt like I was running on a treadmill that was slowly moving backward. It turned out I was obsessing over the wrong figure. I was looking at my total debt, while the algorithms were staring intently at my balance-to-limit ratio—otherwise known as credit utilization. I was trying to climb a mountain while my boots were still tied together. Today, I want to help you untie those laces. We are going to dive into why your utilization is the absolute king of your credit report and how you can master it without needing a lottery win.
Why the Banks Care More About Your Limits Than Your Payments
Most of us are taught that “debt is bad,” so we assume that paying off any debt is a win. I made the classic mistake of paying off my low-interest car loan while leaving my high-interest credit card hovering at 90% of its limit. I thought I was being smart. I wasn’t. In fact, this is exactly why your credit score stalled after that big payment you thought would change everything. The truth is, lenders view a maxed-out card as a sign of financial distress, even if you have the cash to pay it off tomorrow. Your credit utilization ratio makes up about 30% of your FICO score. According to data from FICO, this is the second most important factor, trailing only your payment history. If you have a $1,000 limit and you’re carrying a $900 balance, you look risky. Even if your total debt is low compared to your neighbor, your *ratio* is what screams “danger” to the bureaus. This is why your available credit is more important than your debt in the eyes of the scoring models. Lenders want to see that you have access to credit but the discipline not to use it all. It’s a paradox, I know. They give you the money but penalize you for using it. But once you accept this rule, you can start winning the game.
Is this utilization thing just a gimmick to keep us in debt?
I get it. It feels like a rigged game. Why should it matter if I use 10% or 90% if I’m making my payments on time? But think of it from the bank’s perspective: someone who consistently uses nearly all their available credit is one “transmission failure” or “medical bill” away from missing a payment. When I finally understood the secret to lowering your debt-to-income ratio and managing my balances, my score jumped 45 points in a single month. It wasn’t magic; it was just math. Today, we’re going to stop the guessing game. I’m going to show you how to manipulate this ratio in your favor, even if you don’t have a spare pile of cash sitting around. Have you ever felt like you were doing everything right, only to see your score drop or stay stagnant? Tell me about your experience in the comments, because I’ve been there too. We can even look into how to use personal loans to fix a high utilization problem if your credit card interest is eating you alive. It’s time to stop worrying about the total and start focusing on the percentage.
Master the AZEO Strategy to Hack the Algorithm
The most powerful tool in your credit-building arsenal is a method known as AZEO, or All Zero Except One. For years, I believed that keeping a small balance of $20 or $30 on every single card proved to lenders that I was an active, responsible borrower. I was dead wrong. I finally sat down, cleared four of my five credit cards to a literal $0 balance, and left just $15 on my primary travel card. Within 30 days, my score jumped by 22 points. The math is simple: the FICO algorithm rewards you for having most of your accounts dormant while one shows a tiny, manageable usage. This is one of the most effective credit repair tips to boost your score today because it proves you aren’t reliant on revolving debt to survive. Think of it like a chef with a dozen knives; you only need to use one at a time to prove you know how to cook. If you use them all at once, you just look like a hazard. 
Request More Space Without Spending a Dime
Another way to manipulate the ratio without actually paying down debt is to expand the ‘bucket’ your debt sits in. I remember calling my primary bank three years ago, terrified they’d think I was desperate for cash. Instead, I simply asked for a credit limit increase based on my consistent on-time payments. They bumped my limit from $3,000 to $7,500 over the phone. Instantly, my $1,500 balance went from 50% utilization to a healthy 20%. The key here is to ensure the lender performs a ‘soft pull’ rather than a ‘hard pull’ on your credit report. You must be careful, however, and learn how to handle a credit card issuer that arbitrarily lowered your limit, as this can happen if they perceive a change in your risk profile. Widening your credit limits is essentially building a buffer between you and a score drop.
Beat the Reporting Clock Every Single Month
Most people treat their credit card like a utility bill—they wait for the statement, then pay it by the due date. If you want a top-tier score, you have to stop doing that. Your bank reports your balance to the bureaus on the statement closing date, which is usually 21 to 25 days *before* your due date. If you spend $2,000 and pay it off on the due date, the credit bureau still sees that $2,000 balance for the entire month. I started setting an alarm for three days before my statement close date to pay my balance down to that ‘AZEO’ level. This is the 5-minute habit that protects your credit score from sudden drops. When you align your payments with the reporting cycle, you’re essentially whispering the right numbers into the ear of the credit bureaus.
Shift Your Debt to a Different Bucket
If your credit card balances are so high that paying them down feels impossible, you might need to change the *type* of debt you’re carrying. Credit scoring models treat revolving debt (cards) much more harshly than installment debt (loans). I once helped a friend move $10,000 of high-interest card debt into a personal loan. Her score spiked 50 points almost overnight because her credit card utilization dropped to zero, even though her total debt stayed the same. It is vital to understand how to use personal loans to fix a high utilization problem without falling back into the trap of charging those cards up again. This is the best strategy for eliminating high interest credit card balances while simultaneously repairing your credit profile. You aren’t just paying debt; you’re re-categorizing it to satisfy the algorithm’s hunger for low revolving ratios. Learning how to use your credit card like a debit card for rewards will ensure that once those balances are gone, they stay gone for good.If you think simply paying off every collection on your report is the ticket to a 700+ score, you are in for a rude awakening. I have seen people flush thousands of dollars down the drain only to see their score plummet. Why? Because when you pay an old, dormant collection account, you risk ‘re-aging’ that debt in the eyes of the scoring model. By updating the ‘last date of activity,’ you can move a negative mark from the forgotten past to the prominent present. This is one of the most dangerous top credit repair myths busted by experts in 2025. Before you send a dime, you must understand the truth about credit counseling vs debt settlement and always negotiate for a ‘pay-for-delete.’ Otherwise, you are just paying for the privilege of a fresh scar on your report.
Stop Settling Without a Deletion Agreement
The biggest ‘oops’ moment I encounter is the consumer who settles a debt but leaves the ‘paid collection’ status behind. To a lender, a paid collection is still a collection—it means you defaulted. You need that line item gone entirely. You should also be wary of how to spot a credit repair scam in seconds, as many firms promise deletions they cannot deliver. Instead, focus on how to remove a paid collection from your credit report permanently by using a goodwill deletion request or a strategic dispute. According to a study by the Consumer Financial Protection Bureau (CFPB), approximately one in five consumers has a verified error on at least one of their three credit reports. This means your first move should not be to pay, but to verify. Have you ever fallen into this trap where paying a debt made things worse? Let me know in the comments.
Why is your Credit Karma score lying to you?
Most people check their score on a free app and think they are ready for a mortgage. Then they sit down with a loan officer and find out their ‘real’ score is 40 points lower. This happens because those apps often use VantageScore, while 90% of top lenders use FICO. This is why VantageScore might be giving you false hope. FICO weights things like ‘length of credit history’ much more heavily. 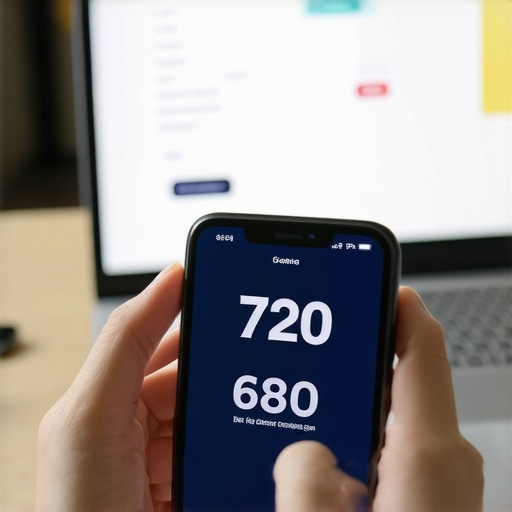
Don’t Fall for the Frivolous Dispute Trap
Everyone tells you to ‘dispute everything,’ but if you send ten generic letters at once, the bureaus will flag your account as ‘frivolous’ and stop looking at your evidence altogether. You need to know the reason you should check your credit report at all three bureaus individually, as each one might have different errors. Use effective credit repair techniques for a fresh financial start by providing specific, documented proof for every claim you make. If the bank truly messed up, learn how to dispute a late payment that was actually the bank’s fault with a targeted letter rather than a shotgun approach. Mastering credit counseling secrets for smarter debt management in 2025 requires moving past ‘beginner’ advice and treating your credit report like a legal document that requires surgical precision.Once you move past the ‘repair’ phase and into the ‘optimization’ phase, your toolkit needs to evolve. I stopped relying on free, surface-level apps years ago because they only give you a fraction of the picture. For my personal finances, I switched to the MyFICO platform. While it costs a monthly subscription, it is the only way to see the 28 different FICO versions that lenders actually use for mortgages, auto loans, and credit cards. This level of granularity is the key to smart debt management practices for maintaining financial health. If you are only looking at one score, you are missing the nuances that could cost you thousands in interest when you eventually go to buy a home.
How do I maintain my credit score without the constant stress?
The secret is automation and ‘micro-audits.’ I have every single one of my revolving accounts set to auto-pay the minimum amount on the due date. This is my insurance policy against life getting in the way. However, I still manually log in three days before the statement closing date to pay the balance down to that ‘AZEO’ level. This is where credit counseling secrets for smarter debt management in 2025 come into play—it is about managing the report, not just the debt. I also use a simple spreadsheet to track my ‘Total Credit Capacity.’ Every six months, I check if I am eligible for a limit increase. By systematically expanding my limits, I ensure that my daily spending never accidentally pushes my utilization above 5%. If you are building credit from scratch what you need to know in 2025 is that your ‘available’ credit is your biggest asset.  The industry is shifting rapidly. According to a technical brief by FICO on their ’10 T’ model, trended data is becoming the new gold standard. This means they aren’t just looking at your score today, but the ‘direction’ of your balances over the last 24 months. I predict that within three years, your utility and rent payments will be just as influential as your car loan. To stay ahead, you need to follow the ultimate credit repair blueprint for 2025 and start reporting those non-traditional payments now. Don’t wait for the banks to catch up; give them the data they want before they even ask for it. My challenge to you today: Log into your primary credit card right now and set up a custom alert for when your balance hits 10% of your limit. This one small notification is the ultimate ‘early warning system’ for your credit health. Keeping your score high isn’t about working harder; it is about building a system that alerts you before a mistake even happens. Once you master this, you can focus on mastering debt management proven strategies for financial freedom and finally stop worrying about the bureaus altogether.
The Hard Truths I Learned While Fighting the Bureaus
Looking back at my journey from a 580 to a 790, I realized that the math was the easy part; the psychology was the hurdle. First, I had to stop viewing credit as a ‘reward’ and start viewing it as a tool. If you treat your limits like a safety net, you’ve already lost. Second, I learned that ‘perfect’ is the enemy of ‘good.’ You don’t need a $0 balance on every card to see a massive jump; you just need to follow the credit counseling secrets for smarter debt management in 2025 that focus on consistency over intensity. Lastly, I realized that the bureaus aren’t your friends, but they aren’t your enemies either—they are simply data aggregators that reward predictability. If you want to win, you have to be the most predictable person they’ve ever seen.
The Only Resources I Still Use to Protect My Score
To stay on top of your game, you need more than just a free app. I personally rely on the AnnualCreditReport.com site for my quarterly deep-dives because it gives me the full, unedited history that lenders see. I also keep a printed copy of the Fair Credit Reporting Act (FCRA) in my desk drawer; knowing my rights has saved me from dozens of predatory collection attempts. For a structured approach to fixing errors, I highly recommend following the ultimate credit repair blueprint for 2025 to ensure you aren’t missing any new regulations. These aren’t just links; they are the exact maps I used to navigate out of the debt woods. If you need a more personalized touch for long-term growth, check out mastering debt management proven strategies for financial freedom to help categorize your spending and repayment plans.
The Path to Financial Freedom is Clearer Than You Think
You have the knowledge now to stop being a passenger in your own financial life. Whether you are starting from zero or fixing a few old mistakes, remember that every small payment and every strategic dispute is a brick in the wall of your future security. Your journey toward how to repair credit fast essential tips for better scores starts with the very next transaction you make. Don’t let the complexity of the system intimidate you. You’ve got the tools, the strategy, and the mindset to win. Once you master the ratio, you master the score.
What is the biggest roadblock you’ve faced when trying to lower your credit utilization or clean up your report? Let me know in the comments below!