How to Read the Fine Print on Your Credit Card Agreement
I stood in my kitchen, staring at a $35 “inactivity fee” on a card I hadn’t touched in six months, feeling that familiar sink in my stomach. I was absolutely furious, but mostly at myself. How could they charge me for not spending money? I realized in that moment that I had signed a legally binding contract I didn’t actually understand. For years, I operated on the naive assumption that as long as I paid my bill on time, the bank and I were on the same team. I was wrong. My early twenties were a chaotic masterclass in making common credit mistakes that could have been avoided with just ten minutes of focused reading. I once ignored a tiny clause about a “penalty APR” and watched my interest rate balloon to nearly 30% just because I was forty-eight hours late on a single payment. It felt like the bank was playing a rigged game where I didn’t even have the rulebook.
Stop Ignoring the Fine Print Before It Costs You a Fortune
Most of us treat credit card agreements like the “Terms and Conditions” on a software update. We scroll to the bottom and hit “Accept” as fast as possible because we want the rewards or the shiny new plastic in our hands. But that wall of tiny text isn’t just boring filler; it’s a legal roadmap of exactly how the bank plans to extract money from your pocket. When I first started building credit from scratch, I thought the only number that mattered was the flashy 0% intro APR. I didn’t realize that hidden factors determine your interest rate long after that honeymoon phase ends. If you don’t know where to look, you’re essentially handing the bank a blank check and hoping for the best. We’re going to fix that today. I’m going to show you the specific sections that actually matter so you can stop worrying about surprise fees and start mastering debt management for good. There is a specific peace of mind that comes from knowing exactly how your creditors operate.
Is reading the whole agreement really worth the headache?
Let’s be real: nobody has the time or the mental energy to read 30 pages of size-8 legalese. You don’t need to be a corporate lawyer, but you do need to be a bit of a detective. According to the Consumer Financial Protection Bureau (CFPB), while credit card agreements are becoming more standardized, they still often contain dense language that obscures costly interest rates and obscure transaction fees that add up over time. I used to think it was a waste of time until I found out I was being charged a monthly “paper statement fee” on a card I barely used. Checking the “Schumer Box”—that handy table required by law—takes five minutes and can save you hundreds of dollars in the long run. It’s the ultimate cheat sheet for your finances. Have you ever been blindsided by a fee you didn’t know existed? I’d love to hear your story—it helps us all stay sharp and keep the banks honest.
Scan for the Schumer Box First
Think of the Schumer Box as the nutritional label on a box of processed food. Just as a label tells you if a cereal is packed with hidden sugar, the Schumer Box tells you if a credit card is packed with hidden costs. This table is mandated by federal law, and it is the single most important part of any agreement. It breaks down the purchase APR, the balance transfer fee, and the late payment penalties into a clear, easy-to-read grid. When I first started digging into these, I found that how to avoid costly interest rates when applying for a new loan starts with identifying the ‘Variable’ rate section. If your rate is tied to the Prime Rate, it can go up even if your credit score stays perfect. Most people skip this and then wonder why their monthly payment shifted by $10 for no apparent reason. 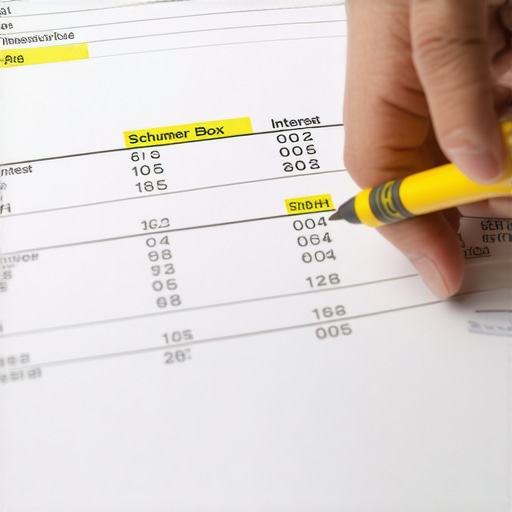
Identify the Invisible Penalty Triggers
Beyond the basic interest rate, you need to hunt for the ‘Penalty APR’ clause. This is the financial equivalent of a tripwire. I once missed a single payment on a retail card by exactly three days. Because I hadn’t read the agreement, I didn’t realize that one mistake triggered a permanent jump from 15% to 29.99%. It took me six months of perfect behavior to get them to lower it back down. If you find yourself in this position, knowing how to remove a late payment from your credit report overnight can help mitigate the damage, but the interest hike often stays until you call and negotiate. Always look for how long the penalty lasts; some banks keep you at that high rate indefinitely.
Practice Smart Debt Management with the Two-Cycle Billing Rule
One of the most confusing parts of an agreement is the ‘Balance Computation Method.’ Most modern cards use ‘Average Daily Balance,’ but some older or predatory cards use ‘Two-Cycle Billing.’ This is essentially charging you interest on money you already paid off last month. It sounds like a scam, but it’s often buried in the text. I remember a specific time I was trying to be responsible and paid off a $2,000 balance in two large chunks. I still saw a massive interest charge the following month because the bank was looking at the average balance across two months instead of one. Implementing smart debt management practices for maintaining financial health means prioritizing cards that use the simple daily balance method.
Check the Fine Print on Credit Limit Changes
Your credit limit isn’t set in stone, and the agreement usually gives the bank the right to lower it at any time without warning. This is a nightmare for your ‘utilization ratio.’ I once had a card with a $5,000 limit that I was using for $1,000 in monthly expenses. The bank suddenly slashed my limit to $1,500 because they saw I was carrying a balance on another card. Overnight, my utilization went from 20% to nearly 70%, and my score tanked. To prevent this, you should regularly learn how to get a credit limit increase without a hard credit pull to keep a healthy buffer.
Avoid the Minimum Payment Sinkhole
The agreement will always list the ‘Minimum Payment’ formula—usually 1% or 2% of your balance plus interest. This is the bank’s favorite part of the contract because it ensures you stay in debt as long as possible. If you only pay that amount, you aren’t just paying slowly; you’re often barely covering the interest. Understanding the truth about credit card minimum payments and your future is vital for anyone mastering debt management. I spent three years paying the minimum on a vacation I took in 2018, only to realize I had paid for that trip three times over in interest alone. Always look for the ‘Total Interest’ disclosure that shows what happens if you take the minimum payment path—it’s the ultimate wake-up call.I stood in my kitchen, staring at a $35 “inactivity fee” on a card I hadn’t touched in six months, feeling that familiar sink in my stomach. I was absolutely furious, but mostly at myself. How could they charge me for not spending money? I realized in that moment that I had signed a legally binding contract I didn’t actually understand. For years, I operated on the naive assumption that as long as I paid my bill on time, the bank and I were on the same team. I was wrong. My early twenties were a chaotic masterclass in making common credit mistakes that could have been avoided with just ten minutes of focused reading. I once ignored a tiny clause about a “penalty APR” and watched my interest rate balloon to nearly 30% just because I was forty-eight hours late on a single payment. It felt like the bank was playing a rigged game where I didn’t even have the rulebook.
Stop Ignoring the Fine Print Before It Costs You a Fortune
Most of us treat credit card agreements like the “Terms and Conditions” on a software update. We scroll to the bottom and hit “Accept” as fast as possible because we want the rewards or the shiny new plastic in our hands. But that wall of tiny text isn’t just boring filler; it’s a legal roadmap of exactly how the bank plans to extract money from your pocket. When I first started building credit from scratch, I thought the only number that mattered was the flashy 0% intro APR. I didn’t realize that hidden factors determine your interest rate long after that honeymoon phase ends. If you don’t know where to look, you’re essentially handing the bank a blank check and hoping for the best. We’re going to fix that today. I’m going to show you the specific sections that actually matter so you can stop worrying about surprise fees and start mastering debt management for good. There is a specific peace of mind that comes from knowing exactly how your creditors operate.
Is reading the whole agreement really worth the headache?
Let’s be real: nobody has the time or the mental energy to read 30 pages of size-8 legalese. You don’t need to be a corporate lawyer, but you do need to be a bit of a detective. According to the Consumer Financial Protection Bureau (CFPB), while credit card agreements are becoming more standardized, they still often contain dense language that obscures costly interest rates and obscure transaction fees that add up over time. I used to think it was a waste of time until I found out I was being charged a monthly “paper statement fee” on a card I barely used. Checking the “Schumer Box”—that handy table required by law—takes five minutes and can save you hundreds of dollars in the long run. It’s the ultimate cheat sheet for your finances. Have you ever been blindsided by a fee you didn’t know existed? I’d love to hear your story—it helps us all stay sharp and keep the banks honest.
Scan for the Schumer Box First
Think of the Schumer Box as the nutritional label on a box of processed food. Just as a label tells you if a cereal is packed with hidden sugar, the Schumer Box tells you if a credit card is packed with hidden costs. This table is mandated by federal law, and it is the single most important part of any agreement. It breaks down the purchase APR, the balance transfer fee, and the late payment penalties into a clear, easy-to-read grid. When I first started digging into these, I found that how to avoid costly interest rates when applying for a new loan starts with identifying the ‘Variable’ rate section. If your rate is tied to the Prime Rate, it can go up even if your credit score stays perfect. Most people skip this and then wonder why their monthly payment shifted by $10 for no apparent reason.
Identify the Invisible Penalty Triggers
Beyond the basic interest rate, you need to hunt for the ‘Penalty APR’ clause. This is the financial equivalent of a tripwire. I once missed a single payment on a retail card by exactly three days. Because I hadn’t read the agreement, I didn’t realize that one mistake triggered a permanent jump from 15% to 29.99%. It took me six months of perfect behavior to get them to lower it back down. If you find yourself in this position, knowing how to remove a late payment from your credit report overnight can help mitigate the damage, but the interest hike often stays until you call and negotiate. Always look for how long the penalty lasts; some banks keep you at that high rate indefinitely.
Practice Smart Debt Management with the Two-Cycle Billing Rule
One of the most confusing parts of an agreement is the ‘Balance Computation Method.’ Most modern cards use ‘Average Daily Balance,’ but some older or predatory cards use ‘Two-Cycle Billing.’ This is essentially charging you interest on money you already paid off last month. It sounds like a scam, but it’s often buried in the text. I remember a specific time I was trying to be responsible and paid off a $2,000 balance in two large chunks. I still saw a massive interest charge the following month because the bank was looking at the average balance across two months instead of one. Implementing smart debt management practices for maintaining financial health means prioritizing cards that use the simple daily balance method.
Check the Fine Print on Credit Limit Changes
Your credit limit isn’t set in stone, and the agreement usually gives the bank the right to lower it at any time without warning. This is a nightmare for your ‘utilization ratio.’ I once had a card with a $5,000 limit that I was using for $1,000 in monthly expenses. The bank suddenly slashed my limit to $1,500 because they saw I was carrying a balance on another card. Overnight, my utilization went from 20% to nearly 70%, and my score tanked. To prevent this, you should regularly learn how to get a credit limit increase without a hard credit pull to keep a healthy buffer.
Avoid the Minimum Payment Sinkhole
The agreement will always list the ‘Minimum Payment’ formula—usually 1% or 2% of your balance plus interest. This is the bank’s favorite part of the contract because it ensures you stay in debt as long as possible. If you only pay that amount, you aren’t just paying slowly; you’re often barely covering the interest. Understanding the truth about credit card minimum payments and your future is vital for anyone mastering debt management. I spent three years paying the minimum on a vacation I took in 2018, only to realize I had paid for that trip three times over in interest alone. Always look for the ‘Total Interest’ disclosure that shows what happens if you take the minimum payment path—it’s the ultimate wake-up call. One of the biggest lies I fell for early on was the idea that “settling” a debt was just as good as paying it in full. It’s not. But here is the real kicker: sometimes, paying an old debt at all can backfire. You’ve probably heard that you should clear your records as fast as possible. However, the nuance most people miss is that paying a six-year-old collection can occasionally update the “date of last activity,” making a dormant negative item look brand new to certain scoring models like FICO 8. In my experience, you should never send a dime until you’ve mastered how to negotiate a pay-for-delete deal with scrappy debt buyers. If the agency won’t agree in writing to remove the tradeline, you are essentially paying for a status that still weighs down your score. 
Why Paying Off Old Debt Sometimes Makes Your Score Drop
Most experts suggest that carrying a small balance month-to-month helps your score. That is a complete myth. According to the Consumer Federation of America, a significant percentage of consumers don’t realize that credit utilization is calculated based on the balance reported on the statement closing date, not the payment due date. You don’t need to pay a cent in interest to have a perfect score. By paying your bill in full before the statement date, you can manipulate your utilization to 1%, which is the “sweet spot” for a boost. For those already in a hole, effective credit repair tips to boost your score today involve timing payments to the statement cycle rather than the calendar month.
Watch Out for the Credit Counseling Invisible Red Flag
Then there’s the credit counseling trap. While nonprofit agencies can be life-savers, many people don’t realize that entering a Debt Management Plan (DMP) can sometimes result in a note on your credit report stating the account is managed by a third party. While this doesn’t lower your score, some mortgage lenders view it as a sign of financial instability. Before you sign up, you must understand the truth about credit counseling vs debt settlement. I’ve seen people qualify for lower rates through a DMP only to be denied a home loan later because of that tiny notation.
Can you really force a credit bureau to delete an accurate late payment?
The short answer is no, but the professional answer is “often.” You can’t legally force the removal of accurate data, but you can leverage the fact that the Fair Credit Reporting Act (FCRA) requires every single piece of data to be 100% verifiable. If a creditor has moved to a new software system or lost the original digital signature of your late payment, they cannot verify it and must remove it. This is why top credit repair myths busted by experts in 2025 emphasize that persistence matters more than legal tricks. Have you ever fallen into the trap of paying an old debt only to see your score stay the same? Let me know in the comments—it helps us all stay sharp and keep the banks honest.I eventually stopped obsessing over the daily fluctuations of my score and started focusing on the systems that keep it high while I sleep. Most people rely on automated apps that categorize their spending, but I found that these tools often mask the problem by doing the thinking for you. If you want to stay in control, you need to be the one holding the wheel. I personally swear by a manual ledger once a month—it’s the best way to track your spending without using a complex app that might sell your data. This manual check-in forces you to confront every single transaction, making it nearly impossible for a hidden fee or an unauthorized charge to slip through.
Ditch the Automated Alerts and Do a Manual Pulse Check
While credit monitoring services are great for catching identity theft, they can make you lazy about your actual debt levels. I’ve seen people maintain a score of 750 while their actual financial health was crumbling because they were just moving debt from one card to another. Real smart debt management practices for maintaining financial health require a quarterly audit where you download your raw data from all three bureaus. You’d be surprised how often a mistake appears on Equifax but not on TransUnion. Understanding the reason you should check your credit report at all three bureaus is the difference between getting a ‘yes’ or a ‘no’ when you finally apply for that mortgage.
How can I maintain a perfect credit profile long-term?
The secret isn’t in some complex legal loophole; it’s in the ‘set it and forget it’ philosophy applied correctly. I keep one small recurring subscription—like a $5 streaming service—on my oldest cards to keep them active and set them to autopay from my checking account. This ensures the account stays open without me having to carry the plastic in my wallet. If you are aiming for the top tier, learning how to get your credit score to 800 and beyond involves this kind of strategic dormancy. 
The Future of Your Score Depends on Trended Data
The game is changing. According to Tom Quinn, Vice President of Scores at FICO, the industry is moving toward ‘trended data’ models like FICO 10T. Unlike older models that only look at a snapshot of your debt today, trended data looks at your behavior over the last 24 months. They want to see if you are ‘transacting’ (paying in full) or ‘revolving’ (carrying a balance). This means that a single month of high utilization won’t tank you as hard as it used to, provided your 24-month trend shows you usually pay it off. This shift makes credit counseling secrets for smarter debt management in 2025 even more relevant, as consistency is now more valuable than quick fixes. If you’re following the ultimate credit repair blueprint for 2025, you should be focusing on long-term payment stability rather than just disputing old items. I challenge you to log into your primary bank account right now and look at your last three months of statement closing balances—if they are trending upward, it’s time to trigger a ‘no-spend’ week to reset your baseline before the new AI-scoring models catch on.
Hard Truths from the Credit Trenches
One of the biggest lessons I’ve learned is that the “date of last activity” is a double-edged sword. If you start looking for how to repair credit fast without knowing your dates, you can accidentally reset the clock on old debt and keep a negative item on your report for years longer than necessary. Another lightbulb moment: the idea that you need to carry a balance to improve your score is a complete lie. You can achieve a perfect score by using credit building hacks that focus on payment timing rather than interest-bearing debt. Lastly, don’t trust the bank to have your back; they are businesses designed to profit from your lack of knowledge. The only way to win is to become the most informed person in the room regarding your own files.
#IMAGE_PLACEHOLDER_E#
Tools That Actually Moved the Needle
I don’t rely on flashy automated apps that might sell my data or mask the root causes of overspending. Instead, I use the best way to track your spending without using a complex app which is a simple manual ledger updated every Sunday morning. This keeps me connected to every dollar and helps me spot those tiny hidden fees before they snowball. For credit reports, forget the one-bureau snapshots provided by most free services. You need the reason you should check your credit report at all three bureaus because discrepancies are more common than you think. I also highly recommend keeping the ultimate credit repair blueprint for 2025 bookmarked as a reference guide for whenever a creditor tries to change the rules on you.
Take Back the Rulebook
Financial freedom isn’t about how much you earn; it’s about how much you keep. By mastering debt management and refusing to be intimidated by 30 pages of fine print, you are not just saving money—you are taking back control of your financial destiny. You don’t need to be a lawyer to win; you just need to be someone who refuses to be ignored. Start today by pulling just one statement and looking for that Schumer Box. Which hidden fee shocked you the most when you finally read your statement? Drop a comment below—let’s warn each other and stay one step ahead of the banks.