How to Save for an Emergency While Still Paying Down Debt
I remember sitting on my kitchen floor three years ago, staring at a $1,200 invoice for a transmission repair, feeling like the world’s biggest idiot. I had just spent months aggressively attacking my credit card balances, throwing every spare penny at the debt. My balances were finally dropping, but my bank account was a desert. When that car died, I had zero cash. My only choice? Swiping the same high-interest credit card I’d just worked so hard to pay down. It felt like running up a down escalator. This ‘all or nothing’ approach was my biggest mistake, and if you’re feeling that same suffocating pressure, I want you to know there is a middle ground that actually works.
The Trap of the Zero-Dollar Savings Account
Honestly, the financial world loves to give you polarized advice. One guru tells you to live on beans and rice and pay every cent to the bank, while another says you should hoard cash like a squirrel in winter. The truth is that life doesn’t pause its chaos just because you’re trying to follow debt management secrets. When you have no safety net, every minor hiccup—a flat tire, a dental crown, a broken water heater—becomes a full-blown financial crisis that forces you back into the cycle of borrowing. I learned the hard way that why you need an emergency fund before paying off debt isn’t just a suggestion; it’s a survival tactic. Early on, I made the mistake of paying off a collection for a tiny amount using my last $200. Three days later, I couldn’t even afford the co-pay for an urgent care visit. That taught me that why your credit score is not a reflection of your wealth is a hard lesson to swallow when your score is 700 but your fridge is empty.
Is it actually worth the hype to save while interest eats your lunch?
You might be skeptical. Why keep money in a savings account earning 1% interest when your credit card is charging you 24%? It seems like bad math. However, the 2023 report from the Consumer Financial Protection Bureau (CFPB) highlighted that nearly 40% of households lack enough liquid savings to cover even one month of expenses, leading to a reliance on high-cost predatory loans. Savings act as a buffer against your debt growing further. We are going to solve this today by finding a balance that lets you sleep at night without letting the interest win. Have you ever felt like you were finally getting ahead only to have an emergency set you back to square one? Smart debt management practices aren’t just about the numbers; they are about your peace of mind. We are going to dive into how to build that cushion without slowing your progress to a crawl, even if you’re currently looking at the first move to make when you can’t pay your bills.
Build a Barrier Before You Attack the Balance
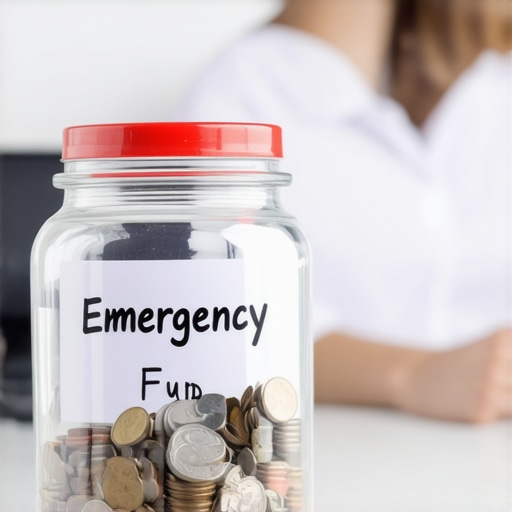
Stop letting the bank dictate your stress levels. My turning point came when I stopped obsessing over the interest and started obsessing over my ‘break glass in case of emergency’ fund. I forced myself to save exactly $1,000 before I paid a single extra cent toward my credit cards. It took six weeks of skipping every takeout meal and canceling three streaming services, but once that money sat in a high-yield account, the debt transformed from a monster into a simple math problem. If you jump straight into the best strategy for eliminating high-interest credit card balances without that cushion, you are essentially driving a car without a spare tire. Eventually, you will hit a nail, and you will be stranded on the side of the road with no choice but to use a high-interest card again. 
Pick Up the Phone and Slash Your Interest Rates
You do not have to accept the APR the bank gave you three years ago. When I was drowning in a 24.99% interest rate, I spent fifteen minutes on the phone with a customer service rep. I told them I was looking at balance transfer offers from other banks and asked if they could match a lower rate. To my shock, they dropped it to 15% on the spot. That one call saved me $80 a month in interest—money that went straight into my savings account. Learning how to negotiate your APR down with a simple phone call is a foundational skill. It’s like finding free money under your couch cushions. That $80 difference is the single most effective way to stop interest from eating your income every single month.
Split Your Extra Cash Between Debt and Dreams
Instead of throwing every spare dollar at the bank, use the ’80/20′ rule. Put 80% of your extra cash toward your highest-interest debt and 20% toward your savings. I used this method when I received a small tax refund last year. Usually, I would have dumped it all on my debt, felt good for five minutes, and then felt broke again. Instead, I followed the advice on how to use your tax refund to jumpstart your credit and split the money. Half went to the card balance, and half stayed in my pocket. When my washing machine leaked two weeks later, I had the cash to fix it. That is how you break the cycle.
Keep Your Credit Score Moving Up While Your Balances Go Down
You don’t have to wait until you are debt-free to start fixing your score. While I was still paying off $15,000 in debt, I began implementing effective credit repair tips to boost your score today. I made sure my utilization stayed below 30% on my smaller cards and asked for credit limit increases—without spending more. This lowered my utilization ratio instantly. If you find the process overwhelming, looking into credit counseling secrets for smarter debt management in 2025 can provide a roadmap you might not have considered. It’s about playing the long game: paying the debt today while preparing for the mortgage or car loan you’ll need tomorrow.Let’s dig deeper into the mechanics that usually stay hidden behind flashy debt-free headlines. You’ve likely heard that paying off a loan is the ultimate goal, but here is a contrarian truth: paying off a debt in full can actually make your credit score drop. This is one of the most common top credit repair myths busted by experts in 2025. When you close an installment loan, you lose the active status of that account and potentially shorten your credit age. I’ve seen people panic when they pay off a $10,000 car note only to see their score tumble by 20 points. Knowing why your credit score drops when you pay off a loan prevents you from making moves right before you apply for a mortgage. Then there is the Consolidation Trap. It sounds like a dream—one low payment to rule them all. However, a study by the Federal Reserve Bank of Cleveland found that many consumers who use a consolidation loan end up with higher overall debt within three years because they don’t address the underlying spending habits. This is exactly why debt consolidation loans often lead to more debt. You clear the cards, see a zero balance, and suddenly feel like you have room to spend again. Without realizing the hidden costs of debt consolidation loans you must know, you’re just moving the shells around on a very expensive table.  Another nuance people miss is the impact of moving debt around. Many assume a balance transfer is a get out of jail free card. While it pauses interest, the inquiry and the new account opening can temporarily bruise your score. Digging into the truth about balance transfers and their impact on your score reveals that if you don’t pay it off during the 0% period, you’re often left with a higher APR than you started with. It’s about being surgical with your finances rather than taking a sledgehammer to them.
Why Did My Score Stall After That Huge Payment?
It’s a question that drives people crazy. You throw $5,000 at a credit card and… nothing happens to your score. Or worse, it moves a single point. This often happens because of trailing interest or because your utilization was already so high that the needle didn’t move past a specific scoring tier. Understanding why your credit score stalled after that big payment is vital for staying motivated. If you find yourself hitting these walls, learning how to effectively use credit counseling to fix your finances can provide the technical expertise to navigate the algorithm. Sometimes, the issue isn’t the amount you paid, but the timing of when the bureau reported it. Have you ever fallen into this trap? Let me know in the comments. We need to look at credit counseling secrets for smarter debt management in 2025 to ensure your hard-earned money actually results in a higher score.I realized early on that getting out of debt is a sprint, but staying out of debt is a marathon that requires the right equipment. To keep my progress from slipping, I developed the 5-minute habit that protects your credit score from sudden drops. Every Saturday morning, while my coffee is brewing, I log into my primary bank account and my credit monitoring tool. I’m not looking for major shifts; I’m looking for the small, annoying errors that like to creep in, such as a double-billed subscription or a late payment marker that shouldn’t be there. If you aren’t careful, you might end up needing effective credit repair techniques for a fresh financial start just because you weren’t paying attention to the details. I personally use a simple Google Sheet linked to Tiller Money because it pulls my raw transaction data without the distracting ads and ‘recommended’ credit cards that clutter most apps. It allows me to see the raw numbers so I can make decisions based on facts, not marketing. When you use these tools, remember why you should ignore the Credit Karma score for official purposes—it’s a great directional tool, but it’s often a VantageScore, not the FICO score that mortgage lenders actually use.
How do I keep my score climbing year after year?
Maintenance is about more than just avoiding mistakes; it is about strategically growing your available credit. Once my high-interest debt was gone, I didn’t stop. I began looking at the mix-shift tactic for diversifying your credit profile. This isn’t about taking on more debt; it’s about showing the bureaus you can handle different types of accounts, like a small credit union loan alongside your cards. This is part of the ultimate credit repair blueprint for 2025 that focuses on long-term stability rather than quick fixes. According to Ethan Dornhelm, Vice President of Scores and Predictive Analytics at FICO, the move toward trended data in the FICO Score 10T model means that lenders are increasingly looking at your financial trajectory over the last 24 months, not just a snapshot of your current balances. This means your consistency today is being recorded as a pattern of reliability for tomorrow. I predict that in the next few years, AI-driven debt optimization will become the standard, where software will automatically move your cash between high-yield savings and debt payments to maximize every penny of interest.  Until then, you are the pilot. You need to learn how to use credit monitoring services without hurting your score to keep a bird’s-eye view of your profile. If you’ve been on the fence, I challenge you to try the ‘Saturday Five’ this weekend—spend just five minutes looking at your accounts. It is the single most effective way to transition from smart credit counseling into true financial independence.
Lessons the Banks Won’t Put in Their Fine Print
Looking back at my journey, there are a few things that shifted my perspective entirely. First, I realized that the bank’s “minimum payment” is actually a trap designed to keep you profitable for them, not a helpful suggestion. Second, I learned that my self-worth was far more tied to my bank balance than my credit score. It’s much easier to sleep with $500 in savings and a 600 score than $0 in savings and a 750 score. Lastly, I discovered that consistency beats intensity every time. You don’t need a massive windfall to change your life; you just need to stop the bleeding. If you’re still feeling stuck, it might be time to look into how to effectively use credit counseling to fix your finances before you try to tackle the mountain alone.
#IMAGE_PLACEHOLDER_E#
My Essential Debt-Fighting Arsenal
You don’t have to do this with just a calculator and a prayer. I personally swear by three specific resources. First, find a solid non-profit guide; I recommend checking the best credit counseling agencies in the country to find someone who actually has your back. Second, use a “Debt Snowball” calculator to see your finish line—it makes the math feel real. Finally, always keep a copy of the ultimate credit repair blueprint for 2025 on hand. It serves as a tactical manual when the credit bureaus decide to play games with your report. These tools turn overwhelming fear into a manageable checklist.
Take the First Step Toward Your New Reality
The heaviest part of debt isn’t the interest; it’s the mental weight you carry every morning. But remember, every expert started exactly where you are—wondering if it was even possible. By implementing these strategies, you aren’t just moving numbers around; you are buying back your freedom. Effective debt management is about more than just paying bills; it’s about creating a life where you control your money instead of your money controlling you. Whether you are starting today or building credit from scratch, the most important move is the one you make right now. Have you ever tried to pay off a huge balance only to see your score stay the same or drop? Let me know your story in the comments below.