The Bureau Tactic That Forces a Manual Review Without a Lawyer
I remember sitting at my kitchen table three years ago, staring at a stack of generic ‘dispute denied’ letters from the big three credit bureaus. It felt like shouting into a void. I had followed every generic tip I found online—standard dispute forms, certified mail, the whole nine yards—and got back the same automated ‘verified’ response within days. It was soul-crushing. My mistake was simple but devastating: I thought a human being was actually reading my letters. I was wrong. Early on, I wasted months using effective credit repair tips to boost your score today that usually work, but my specific file was stuck in an automated loop. I eventually realized that the bureaus’ scanners were flagging my templates as ‘frivolous’ before a human eye even caught a glimpse of them. Today, I am going to show you the exact tactic that breaks that cycle. We are talking about the specific move that forces an actual person to look at your file, ensuring your evidence isn’t just tossed into a digital shredder.
The Automated Rejection Machine is Killing Your Progress
The hard truth is that the credit bureaus are not in the business of helping you. They are data aggregators. When you send a dispute, it often goes through a system called e-OSCAR, which reduces your complex financial history into a two-digit code. According to a report by the Consumer Financial Protection Bureau, these agencies have historically struggled to provide meaningful human review, often spending minimal time actually investigating consumer claims. This is why you feel like you are hitting a brick wall. If you want to see real movement, you have to learn the move that forces a response from credit bureaus that they cannot ignore. I had to learn this the hard way after my third ‘frivolous’ designation, and it changed everything for my score. Have you ever felt like you were arguing with a computer that just wouldn’t listen to reason?
Does a Simple Letter Really Beat the Bureau Robots?
You might be skeptical. I certainly was. It sounds too easy to say that a specific type of correspondence can bypass a multi-billion dollar automation system. But the secret lies in the Fair Credit Reporting Act (FCRA) itself. When you demand a ‘Method of Verification,’ you aren’t just asking them to check their computer again; you are legally requiring them to tell you who they talked to and how they verified the info. Using the method of verification letter every credit repair diyer needs puts the burden of proof back on them. This isn’t about some ‘secret legal loophole’—it is about demanding the manual oversight you are already entitled to by law. We’re going to dive into how to structure this so you can finally remove negative items from your credit report fast without waiting for a lawyer to charge you a thousand dollars for the same result.
Ditch the Printed Forms and Get Messy
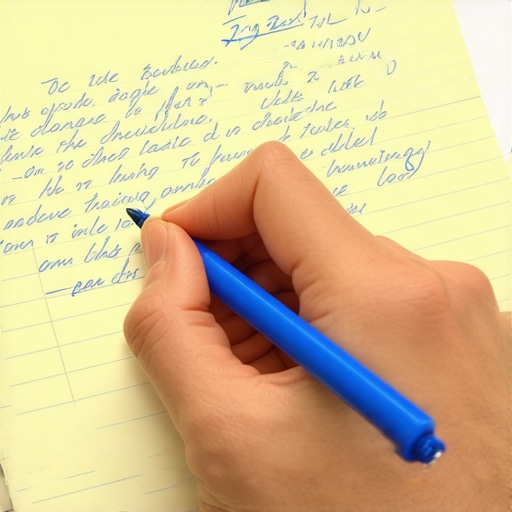
The first thing you need to do is stop using those sleek, perfectly typed templates you found on a forum. Think of the credit bureau’s intake facility like a giant mailroom where high-speed scanners are the gatekeepers. When you send a crisp, laser-printed letter with a ‘Reason Code 101’ written in Arial font, you are essentially handing a target to a robot. To beat the system, you have to look like a person, not a law firm. I remember being so frustrated that I finally grabbed a yellow legal pad and a blue ballpoint pen. I wrote my dispute by hand, slightly slanted, and didn’t even use a ruler. I mentioned a specific medical bill that was haunting me and simply asked, ‘Where did this come from? I don’t recognize it.’ By not using the standard jargon found in the ultimate credit repair blueprint for 2025, my letter couldn’t be automatically categorized. It landed on a real person’s desk. That one ‘messy’ letter did more for my score in 30 days than six months of typed correspondence did.
Your Handwritten Letter Bypasses the Robots
Why does handwriting work? It’s simple: automation is expensive to program for every variation of human penmanship. When the OCR (Optical Character Recognition) software can’t confidently read your letter, it triggers a ‘manual exception.’ This is exactly where you want to be. While you are doing this, you should also be looking at how to avoid the most common credit repair mistakes, like forgetting to include a copy of your utility bill and ID. If a human opens your envelope and finds a handwritten note with clear identification, they are legally obligated to open a manual investigation. This is the stage where the ‘Method of Verification’ becomes your sharpest tool. You aren’t just saying ‘this is wrong’; you are forcing them to prove it is right.
Demand the Method of Verification Directly
Once you’ve broken the initial automated barrier, you need to pivot to the Method of Verification (MOV). This is the ‘I want to speak to the manager’ move of the credit world. Under the FCRA, you have the right to request a detailed description of how the bureau verified the information. Did they just check their own digital records? Or did they actually contact the original creditor? Most of the time, they just ping the same database that has the error. By using how to dispute a debt when the creditor has no proof, you are pointing out that a digital ‘yes’ from a computer is not legal verification. In my case, I demanded to see the name and phone number of the person at the hospital who ‘verified’ my old debt. They couldn’t provide it because that person didn’t exist in their logs. The account was deleted forty-eight hours later.
Force the Bureau to Show Their Evidence
If the bureau responds with a generic ‘verified’ letter, don’t panic. This is where you send the second strike. You send a follow-up letter—handwritten again—specifically referencing Section 611(a)(7) of the FCRA. Tell them their previous response was insufficient and that you require the specific procedure used to verify the item. This is often how people remove a late payment from your credit report overnight when the creditor is too lazy to respond to the bureau’s manual inquiry. It turns the credit repair process from a passive wait-and-see game into a focused legal demand. You are essentially putting them on notice: if they can’t show the work, the negative item has to go. This level of persistence is what separates those who stay stuck from those who see their scores climb into the 700s.
I’ve seen people write checks for thousands of dollars to settle old debts, thinking it is the golden ticket to a mortgage. It isn’t. In fact, if that debt is five years old, simply paying it off might update the ‘date of last activity,’ making a stale negative mark look fresh to the algorithm. You have to be surgical. Instead of just paying, you need to understand how to remove a paid collection from your credit history before you part with your cash. This is one of those top credit repair myths busted by experts in 2025: the idea that a ‘paid’ status is just as good as a deletion. It’s not. Most mortgage lenders still use older FICO models that don’t ignore paid collections, meaning you could spend your savings and still have a trash score.
Why Paying Off Collections Can Sometimes Backfire
The nuance that the big banks won’t tell you is that credit scoring is more about recency than morality. When you pay an old, dormant collection, you are essentially waking up a sleeping giant. FICO’s own documentation suggests that while their newer versions (like FICO 9) ignore zero-balance collections, the vast majority of the industry is still stuck on FICO 8 or older. This is why why your credit score hits a plateau and how to break it often involves leaving old debts alone unless you have a ‘pay-for-delete’ agreement in writing. I’ve watched friends try to do the ‘right thing’ only to see their score drop twenty points overnight because they touched an account that had been quiet for years. Have you ever fallen into this trap? Let me know in the comments.
Can a Debt Consolidation Loan Actually Make You Poorer?
Another common mistake is the rush toward consolidation. Everyone tells you to move your high-interest debt to a single personal loan, but this is a dangerous game. According to a study by the Journal of Financial Planning, consumers who consolidate often end up with higher total debt loads within two years because they don’t address the underlying spending habits. They see those zero balances on their credit cards and feel like they have ‘won,’ only to max them out again. You need to look into the truth about consolidation loans and your wallet before you sign that contract. If you don’t close the tap, you’re just moving water around a sinking ship. This is a primary reason how to avoid the most common credit repair mistakes is so vital; it’s about psychology, not just math.
Stop Chasing the 800 Score Until You Fix This One Error
The ‘Oops’ factor that kills many DIYers is the urge to clean up their report by closing accounts. I’ve seen people close their oldest credit card because they don’t use it anymore, thinking they are tidying up their financial life. In reality, they just nuked their ‘length of credit history,’ which accounts for 15% of their score. You need to realize why closing old accounts destroys your score instantly. Your oldest account is your anchor; without it, you’re drifting. Instead of closing things, focus on credit counseling secrets for smarter debt management in 2025 that teach you how to keep those accounts active with small, automated subscriptions. Mastering these nuances is the difference between a temporary boost and a permanent lifestyle of low-interest rates and financial ease.
Once the deletions start rolling in, the temptation is to breathe a sigh of relief and stop looking. That’s exactly how I ended up right back where I started a decade ago. Credit isn’t a ‘set it and forget it’ system; it’s a garden that needs constant weeding. My weapon of choice isn’t some fancy $30-a-month subscription service that just regurgitates data. It’s a simple, physical accordion folder where I keep every single piece of correspondence from the bureaus. If they re-insert a deleted item—which happens more often than you’d think—having that previous ‘deletion’ letter is your only real defense. I learned that using the best way to organize your bills without an app is actually more effective for credit repair because paper trails are harder for legal departments to ignore than a screenshot of an app.
Don’t Let Your Hard-Won Progress Slip Away
The goal of scaling your credit health is to move from ‘repair’ to ‘management.’ When I was at a 520, I was desperate. Now that I am in the 700s, I am tactical. I recommend a quarterly ‘Deep Audit.’ This isn’t just checking your score on your phone; it’s about sitting down and looking at the raw data for inconsistencies. You need to verify that smart debt management practices for maintaining financial health are actually reflecting on your file correctly. Sometimes a lender will report a ‘late’ status even if you paid on the 30th day, purely because of a batch processing error. If you aren’t looking, that error becomes permanent after seven years.
How do I keep my score high for the long haul?
It comes down to a rotation strategy. Every four months, I pull one report from one of the three bureaus via the federally mandated site. This allows me to see the reason you should check your credit report at all three bureaus throughout the year without paying a dime in fees. You also need to why you should ignore the vantagescore and watch your fico because the ‘free’ scores provided by most bank apps use a model that 90% of lenders don’t even use for high-stakes loans. If you are preparing for a mortgage, looking at the wrong score is like checking the temperature in Celsius when the thermostat is in Fahrenheit—you’re going to be very confused when you get to the closing table.
The New Wave of Trended Data is Changing Everything
The industry is shifting toward what is known as ‘Trended Data.’ According to FICO’s technical specifications for the FICO 10T model, lenders are no longer just looking at a snapshot of your debt today. They are looking at your trajectory over the last 24 months. Are you paying down balances, or are you just paying the minimum and letting interest compound? This means your long-term habits are becoming more important than a one-time score boost. If you want to know how to get your credit score to 800 and beyond, you have to show a consistent downward trend in your utilization ratios. This shift makes it even more critical to know how to get your credit report for free without hidden fees so you can spot these trends before a lender does. Try this: Set a calendar alert for exactly four months from today. Go to the official AnnualCreditReport site and pull just your TransUnion file. Look for one specific thing: any address you haven’t lived at in five years. Disputing those old addresses is the easiest ‘stealth move’ to prevent old debts from being linked back to your new, clean profile.
The Brutal Truths I Learned While Fighting the Bureaus
Looking back on my journey, the biggest lightbulb moment was realizing that the bureaus don’t just ‘make mistakes’—they operate on a system designed to discourage the persistent consumer. I learned that my anger was a distraction; what I actually needed was a clinical, evidence-based approach. Another hard lesson was that ‘good enough’ doesn’t cut it when you are dealing with a 500-page automation manual. You have to be the squeaky wheel that the robot can’t ignore. Lastly, I realized that credit counseling insights unlock your path to better credit only when you combine that advice with your own documentation. The system isn’t rigged against you personally; it’s just rigged for efficiency, and your job is to interrupt that efficiency until you get results.
My No-Fail Toolkit for Financial Recovery
If you want to move from defense to offense, you need more than just hope. I swear by three specific things. First, keep a physical copy of the Fair Credit Reporting Act (FCRA) Section 611 highlighted on your desk. When you know your rights, you speak with a different level of authority. Second, use a high-quality blue ink pen for all your disputes—it’s the simplest way to prove a human being touched that paper. Finally, I always recommend looking at the stealth move to fix a 500 credit score fast to understand how to prioritize which items to attack first. Organization is your greatest weapon against a multi-billion dollar data aggregator.
#IMAGE_PLACEHOLDER_E#
Why Today is the Perfect Day to Start Your Comeback
You don’t need a degree in finance or a high-priced attorney to take back your financial life. You just need the willingness to send one letter at a time and the patience to wait for the law to do its job. Using effective credit repair techniques for a fresh financial start isn’t about gaming the system; it’s about making the system work the way it was legally intended to. Your future self—the one who qualifies for that low-interest mortgage or that dream car—is counting on the work you do this afternoon. Don’t let another month of high-interest rates slip by. You have the tools, the tactics, and the rights to demand better. Which negative item has been the hardest for you to remove from your report so far? Let me know in the comments below.