Why Closing Your Oldest Account is a Financial Disaster
It was a rainy Tuesday afternoon when I decided to clean up my financial life. Armed with a cup of black coffee and a surge of organizing energy, I logged into my bank portal. I saw it sitting there: my very first credit card, a dusty, unused relic with a tiny $500 limit and a design that screamed 2012. I had not touched it in years. Feeling a sense of proud accomplishment, I clicked the button to permanently close the account. I thought I was being responsible. I thought I was tidying up my financial house. Instead, I had just lit a match and tossed it directly onto my credit score.
The Day My Credit Score Plummeted 80 Points
Within a few weeks, my score didn’t just drop; it nose-dived off a cliff. I was stunned. I had never missed a payment, my balances were low, and I was actively trying to follow a solid ultimate credit repair blueprint. Yet, there I was, staring at a massive point drop all because of one simple click. What I did not realize at the time is that why closing your oldest card is a massive mistake comes down to how scoring models calculate your credit age and available credit. By deleting that old card, I instantly shortened my average credit history and spiked my overall utilization ratio.
Today, my goal is to make sure you never make the same painful mistake I did. We are going to look under the hood of your credit report so you can protect your hard-earned score without accidentally destroying your credit age. This is not just about keeping a piece of plastic in your drawer; it is about protecting your financial leverage for future loans and mortgages.
Is keeping an old, useless card open actually worth the hassle?
I get it. You do not want a dozen open cards floating around, and you might worry about identity theft or annual fees. According to research published by the Consumer Financial Protection Bureau, the length of your credit history accounts for roughly 15% of your FICO score. That is a massive chunk of your overall rating controlled entirely by how long your accounts have been open. If you close that anchor card, the credit bureaus eventually stop counting that history, which can disqualify you from the best interest rates. Have you ever closed an old account thinking you were doing the right thing, only to watch your credit score take an unexpected hit? Drop a comment or reach out through our contact page to let me know your story.
How Credit History Length Dictates Your Financial Future
Your credit history is like a resume. If you delete your first ten years of work experience, employers will assume you are fresh out of school. Lenders view your credit age in the exact same light. They want to see how you have handled borrowing money over a long, continuous period. When you are looking to start fast-tracking your credit score, protecting those old accounts is the easiest passive boost you can maintain. You do not have to spend a dime on them; you just need to keep them alive.
When I was looking for ways to undo the damage of my closed account, I realized that keeping a card active doesn’t mean you have to spend hundreds of dollars on it. In fact, doing that can land you right back into the danger zone of high interest rates and ballooning balances. Instead, you need a systemized approach to keep these cards awake without letting them clutter your mental space or your wallet.
The Set-and-Forget Automation Method
The biggest threat to an idle credit card isn’t you using it; it is the bank closing it due to inactivity. Banks regularly audit their portfolios and trim away what they call “dormant accounts” to reduce their own risk. To combat this, I developed a simple three-step automation technique that keeps the card active with zero daily effort on your part.
Link a Tiny Recurring Subscription
Find your oldest, dustiest card and link it to a single, small recurring monthly charge. This could be a cheap streaming service, a cloud storage fee, or even a digital newspaper subscription. This small transaction sends a signal to the bank’s automated systems that the account is still alive and well. To make this work seamlessly, you must understand the best time of month to pay your balance for a score boost to ensure this small charge never lingers long enough to accumulate interest.
Put Your Payments on Autopay
Once the monthly charge is established, log into your bank portal and set up automatic payments from your primary checking account to pay off the full statement balance every single month. By automating this, you guarantee you will never miss a payment, which protects the payment history portion of your score—the single largest factor in your credit profile. If you are currently dealing with larger financial hurdles, integrating this automated trick can be a valuable part of smart credit counseling how to rebuild your financial life without adding daily stress to your routine.
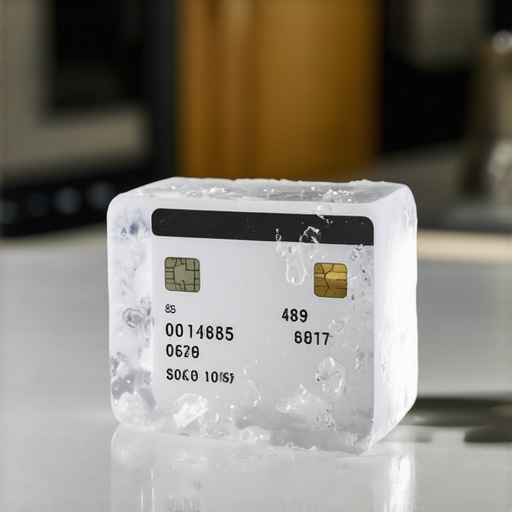
Freeze the Physical Card
After setting up the digital link and the autopay, take the physical piece of plastic and put it somewhere inaccessible. I literally froze mine in a block of ice inside a Tupperware container in my freezer. Some people put theirs in a safe-deposit box or a drawer at their parents’ house. The goal is to remove the temptation of using the card for impulse purchases. This keeps your overall credit utilization low, which is a massive lever when implementing the utilization hack that boosts your score by 30 points almost overnight.
How to Handle Cards with Sneaky Annual Fees
What happens if your oldest card carries a high annual fee that eats away at your budget? Keeping it open just for the credit age might feel like you are throwing money out the window. This is where most people panic and hit the “cancel account” button, but there is a much smarter backdoor strategy that preserves your history without costing you a dime.
Request a Product Downgrade
Instead of closing the account, call the customer service number on the back of your card and ask for a product change or a downgrade. Tell the representative you want to transition your card to a no-fee version within the same card family. For example, if you have a premium rewards card with a $95 annual fee, ask to downgrade it to their basic cash-back card with a $0 annual fee. Because this is a product change rather than a new application, the bank will transfer your entire credit history, opening date, and credit limit over to the new card. You get to keep your decades of history without paying another annual fee. This is one of those highly effective, lesser-known effective credit repair tips to boost your score today that saves your budget and your credit profile simultaneously.
When most people set out to fix their financial profile, they follow the same well-worn path: they pay down small balances, send generic dispute templates they found online, or consider settling their old accounts. But after years of analyzing credit profiles, I have realized that the mainstream financial advice given to consumers is not just outdated—it is actively harming their scores. The credit bureaus and scoring models operate on strict, algorithmic math, not common-sense ethics. If you want to master this system, you have to look past the superficial advice and understand the hidden mechanics that actually dictate your score.
The Great Debt Settlement Trap That Quietly Destroys Credit
The most common advice given to people struggling with debt is to negotiate a settlement. While settling for less than you owe sounds like a win for your wallet, it can be an absolute disaster for your FICO score. Everyone says that resolving your debts is the most important step to recovery, but in my experience, the status of that resolution matters far more than the act of paying itself. When you settle a debt, the creditor updates the status on your credit report to “Settled for Less Than Full Balance.” To a scoring algorithm, this status is nearly as damaging as a fresh delinquency because it proves you did not fulfill your original financial obligation.
Furthermore, settling an account can accidentally reset the reporting clock. Debt collectors often use sneaky tactics to keep ancient accounts active on your report. If you make a partial payment without a written agreement, you might accidentally restart the statute of limitations on an old debt. This is why you must understand why debt management plans are different from risky settlement programs. A structured plan preserves your credit integrity, whereas aggressive settling can leave your report scarred for seven years.
Why does paying off an old collection sometimes make your credit score drop?
This is the ultimate paradox of credit repair. You pay off an old, dusty collection account, expecting your score to shoot up, only to log in the next month and find it has dropped by thirty points. This happens because of how credit scoring models evaluate the “date of last activity.” An old, unpaid collection from five years ago hurts your score, but its impact fades over time. The moment you pay it, the collection agency updates the account status to “paid.” This update flags the account as active, bringing that negative history back to the front of the line. Suddenly, the algorithm treats a five-year-old mistake as if it happened yesterday.
To bypass this trap, you should never pay a collection agency unless they agree to a written pay-for-delete agreement. According to a study by the National Consumer Law Center, millions of consumer profiles contain outdated or misleading collection information that could easily be disputed or negotiated down without damaging the consumer’s current score. Navigating these nuances is the core difference between basic DIY attempts and credit counseling insights avoid common pitfalls in debt management.
Before you make your next payment or close another account, take a step back and look at the bigger picture. Are you treating the symptom of your credit issues, or are you strategically fixing the underlying system? It is incredibly easy to fall into these algorithmic traps when you do not have a clear roadmap. Have you ever fallen into this trap of paying off an old debt only to watch your credit score take an unexpected dive? Let me know in the comments below, or reach out directly on our contact page so we can map out a safer strategy for your financial future.
When you transition from immediate emergency damage control to long-term asset management, your daily routine has to change. I used to spend hours manually auditing my balances, terrified that a single misplaced charge would send my hard-earned score spiraling back down. That is why I had to systematize my approach using specialized tools that take human error completely out of the equation. I do not rely on generic financial trackers anymore. Instead, I personally use a combination of automated calendar alerts synced directly to my banking portal’s statement closing dates, alongside highly targeted monitoring tools that verify my true FICO 8 and FICO 9 scores, rather than the volatile educational scores most free apps provide.
The Tools I Rely on to Automate My Financial Protection
You do not need a bloated suite of expensive software to keep your credit running like a well-oiled machine. In fact, overcomplicating your toolkit often leads to abandonment. I recommend a simple, dual-layered approach. First, utilize your bank’s native custom alert features. Set up an alert for any transaction over $1.00 on your dormant accounts. This ensures that if your automated subscription price changes or if someone compromises your frozen card, you will know within seconds. Second, use the official annual reporting systems to pull your full disclosure files. I personally set a recurring calendar event every four months to review one of the three major bureaus individually. This staggered review strategy gives me year-round oversight without paying a single penny in monitoring fees.
How do I maintain my credit score over time without stress?
The secret to effortless maintenance is creating a simple monthly cadence. Once you have used effective credit repair techniques for a fresh financial start, you only need fifteen minutes a month to audit your setup. On the first of every month, check your primary checking account to ensure your automated payments cleared successfully. Then, verify that your credit utilization across all active cards remains under 10%. If you notice a balance creeping up, you can easily deploy the 15-15 rule for paying off credit card balances effectively to keep your reporting metrics pristine. Consistent, small actions will always beat occasional, frantic damage control.
Where the Future of Credit Repair and Management is Heading
The entire financial scoring landscape is on the verge of a massive technological shift. According to recent whitepapers published by FICO regarding their upcoming FICO 10T and UltraFICO models, historical trended data is going to play a much larger role than ever before. This means the algorithms will not just look at a snapshot of your credit utilization today; they will analyze your spending and payment trajectories over the past 24 months. If you are consistently carrying balances month-over-month, even if they are small, your score could feel the squeeze. Conversely, if you establish a consistent history of paying off your balances in full every month, these new predictive models will reward you with a significant scoring boost. To thrive in this automated future, mastering smart debt management practices for maintaining financial health is no longer optional—it is the baseline for securing competitive interest rates.
This shift toward trended data makes your current automation habits incredibly valuable. By setting up your systems today, you are actively training the future AI algorithms to view you as a low-risk borrower. If you are ready to take immediate, proactive control of your financial profile, I challenge you to try just one advanced strategy today: call your oldest card provider right now and request a product downgrade to a no-fee alternative. It takes less than ten minutes, costs nothing, and permanently secures your oldest credit anchor.
The Hardest Lessons I Learned Managing My Own Financial Recovery
When I first started fixing my credit, I made almost every mistake in the book because I followed standard internet advice. It took years of trial and error to realize that the system does not reward common sense; it rewards algorithmic compliance. Here are the reality checks that completely transformed how I approach my finances:
- Paying off debt does not automatically fix your score. I used to think zero balances across the board was the ultimate goal, but why your credit score flatlined despite monthly payments showed me that the algorithm requires active, positive utilization data to keep moving upward.
- Bureaus are not your friends. They are private, for-profit databases. Waiting around for them to voluntarily correct mistakes is a losing strategy. You have to be aggressive, precise, and systematic with your disputes.
- One closed account can erase years of progress. Keeping your oldest accounts active is the ultimate passive strategy. If you have already made the mistake of shutting down an account, check out my guide on why closing your oldest credit card is usually a mistake to understand how to rebuild that foundation.
My Essential Blueprint for Tracking and Protection
You do not need to spend hundreds of dollars on premium software or sketchy repair agencies to protect your financial standing. I keep my entire system lightweight, secure, and completely free by relying on these specific resources:
- AnnualCreditReport.com: This is the only federally mandated site to pull your real, raw disclosure files from Equifax, Experian, and TransUnion. I recommend reviewing your files using a staggered the 3-step review for your annual credit report schedule every four months.
- Your Bank’s Native Alerts: Instead of bloated monitoring apps, configure your checking account to send real-time push notifications for any transaction over $1.00. It is the fastest, zero-cost way to catch fraud or unauthorized subscription renewals instantly.
- FICO-Focused Dashboards: Avoid relying on volatile educational scoring models. Focus strictly on your FICO 8 and FICO 9 scores, which are the actual metrics utilized by 90% of top-tier lenders.
Take the First Step to Reclaim Your Financial Leverage
The journey to excellent credit is not a sprint; it is a series of small, automated habits that protect your score while you live your life. You do not have to fix everything overnight. By implementing just one small strategy today—like setting up a micro-subscription on an old card or requesting a product downgrade—you are putting up a defensive shield around your financial future. If you want to take your strategy to the next level, our ultimate credit repair blueprint for 2025 is the perfect roadmap to guide your next moves.
Have you ever had your credit score drop unexpectedly after trying to do the right thing, like closing an old account or paying off a collection? Let me know in the comments below, and let’s figure out how to get those points back!